


In Singapore, the majority of businesses turn to business loans when they need working capital for growth. However, what many may not realize is that their ability to secure a loan hinges on the shareholders' credit score. In this informative piece, we delve into the Credit Bureau Singapore (CBS) report and the concept of a credit score and provide insights into maintaining and improving it.
What Exactly is a Credit Score?
A credit score is a numerical representation of an individual's creditworthiness, calculated based on various factors such as loan applications, credit bureau reports, and performance on existing loans. This score serves as an estimate of the likelihood that an applicant will repay a loan successfully. Typically, credit scores are presented as a range of values, for instance, 1000 to 2000. Individuals with lower scores are more likely to default on payments, while those with higher scores are deemed more reliable borrowers.
Checking Your Credit Score in Singapore
To access your credit score, you can request a credit report from the Credit Bureau Singapore (CBS). You have two options: request a soft copy online or obtain a hard copy at select SingPost outlets, the CBS office, or CrimsonLogic Service Bureaus. Be aware that there is a fee involved, currently set at S$8 with additional charges for certain delivery methods. Notably, if you've recently applied for a credit facility with any CBS member, you are entitled to a free credit report.
Understanding Credit Score Categories
Credit scores are not categorically "good" or "bad." The evaluation depends on the specific loan product and the lender's risk tolerance. Your credit score influences the cost of the loan and whether your application is approved. Applicants with higher scores often secure loans with more favorable interest rates. Conversely, individuals with lower scores may struggle to secure a loan, and if they do, the terms and interest rates may be less favorable.
The Impact of Credit Scores on Loan Eligibility
At various banks, a "cut-off" or base score is employed in lending decisions. Applicants whose credit scores fall below this threshold are typically declined, while those above it may be approved, provided they meet additional affordability and verification requirements. This "cut-off" ensures that the bank only accepts customers whose risk profile aligns with its risk appetite for the specific product.
Other Factors Considered in Loan Applications
Lenders may also consider various other factors during loan applications, including annual income, employment history, bankruptcy or litigation records, and the number of credit facilities. For precise details about SCB's product-specific criteria, refer to the supporting credit risk policy.
So what really affects your credit score?
These factors impact the credit score that is provided by CBS:
- Available Credit: The number of open or active credit accounts. Having too many credit lines may lower your score.
- Recent Credit: Spacing out credit applications is advisable. Applying for multiple credit facilities within a short period suggests financial strain.
- Enquiry Activity: Each loan application generates an inquiry. Numerous inquiries can reduce your credit score as it may appear you're taking on excessive debt.
- Utilization Pattern: This indicates the amount of credit used on your accounts. Higher utilization implies a greater debt burden, which can reduce your score.
- Account Delinquency Data: Late payments signal overspending and debt, negatively impacting your score.
- Credit Account History: A history of timely payments boosts your credit score compared to someone with limited credit history.
Improving Your Credit Score in Singapore
Your credit report reflects your financial behaviour over the past 12 months. This means that you can improve your score if you consistently manage your credit behaviour for 12 months. Here are some tips:
- Stay within Existing Credit Limits: Avoid maxing out your credit cards; maintaining a comfortable utilization rate is key.
- Manage Credit Card Payments Wisely: Paying only the minimum amount each month can lead to high-interest costs. Strive to pay your credit card balance in full monthly.
- Control Your Total Credit Exposure: Avoid holding numerous credit cards as it may suggest potential over-indebtedness.
- Demonstrate Low Risk Management: Managing existing credit products responsibly can strengthen your credit score.
- Avoid Rapid Credit Applications: Applying for multiple non-mortgage credit products in a short period can make you appear "credit hungry."
CBS Interpretation
But before you see how to improve your score, it is important to know how to Interpret Your Credit Report.
Your credit report contains various sections:
1) Summary of Credit Report
This includes the date of your earliest known credit account, previous inquiries, the number of accounts you own, defaults, bankruptcy proceedings, secured and unsecured credit limits, Debt Management Programme (DMP) status, ID theft, and narratives.

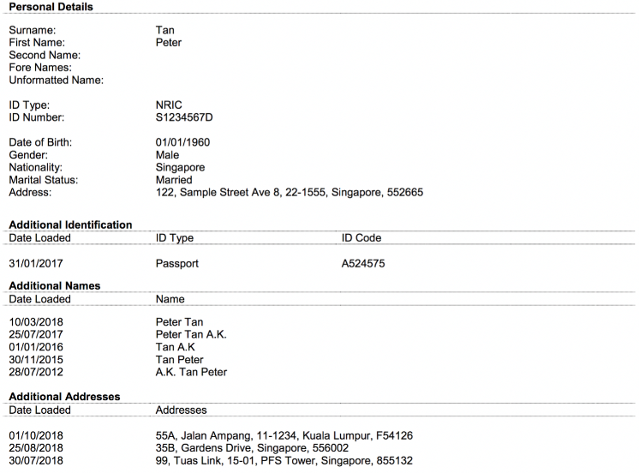
2) Personal Details and Additional Addresses
Used for verification purposes.
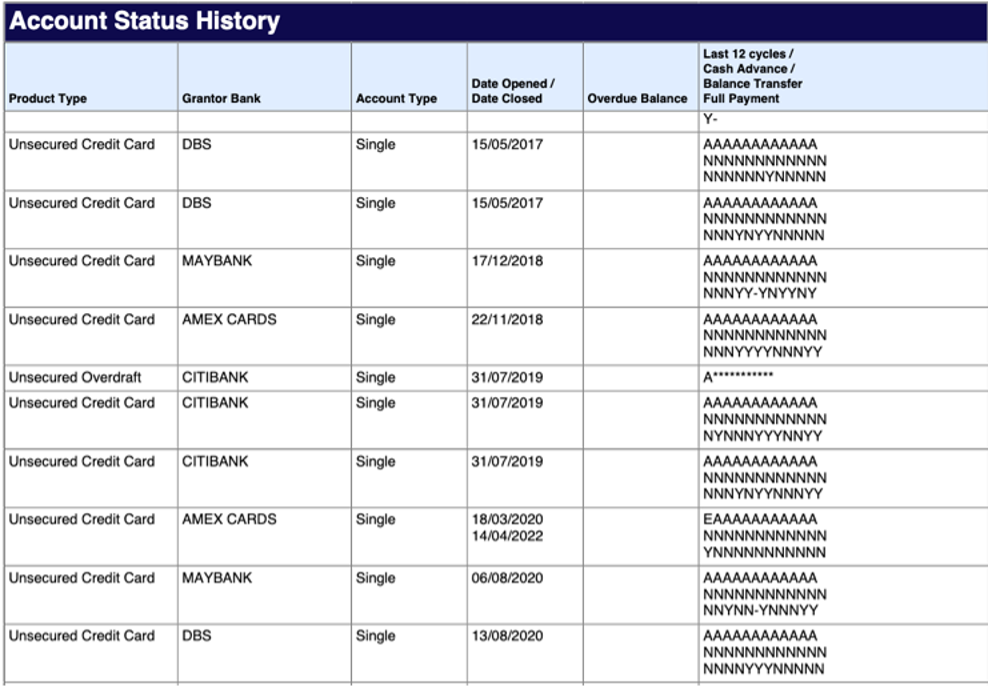
3) Account Status History
Displays all your credit facilities and repayment activity in the last 12 months. For credit card facilities, there will be a
- 2nd row to indicate the status of cash advances or balance transfers and
- 3rd row to indicate status of full payments being made.
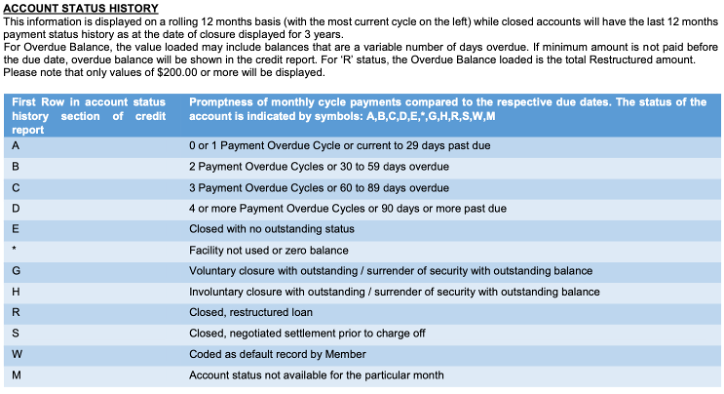
Full legend is as per below:
4) Previous Inquiries
Records all lender inquiries in response to loan applications.

5) Default Records
Lists payment defaults on your credit facilities.

6) Debt Repayment Scheme (DRS) Records
Records DRS activity and status.

7) Bankruptcy Proceedings
Displays bankruptcy records.

8) Credit Score
Your credit score is prominently displayed.


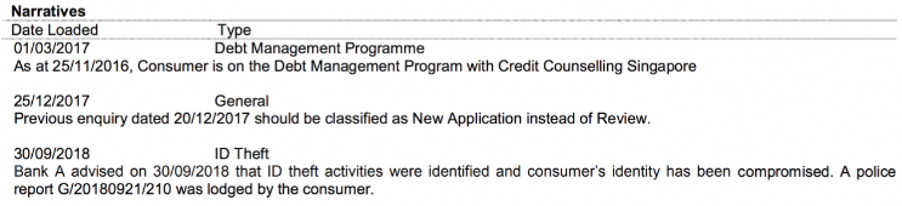
9) Narratives
Miscellaneous comments provided by third parties.
10) Aggregated Outstanding Balances
Records outstanding balances based on unpaid amounts under your credit facilities.
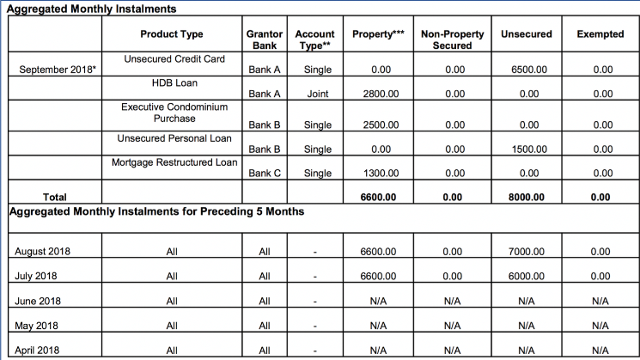
11) Aggregated Monthly Instalments
Records monthly instalments for each credit facility for the previous and upcoming months.
Frequently Asked Questions
1. When is an account classified as a default?
This constitutes a business choice made by the credit provider and can hinge on several considerations. Typically, an account will be designated as in default after it remains overdue for 90 days or more. It's important to note that Credit Bureau (Singapore) doesn't dictate when an account is categorized as in default; instead, it mirrors this information once the bank has officially classified it as such.
2. How long does information remain on my credit report?
The importance of each type of information varies in the assessment of creditworthiness. Consequently, the credit report retains information to assist members in their creditworthiness evaluation as follows:
- Details about Previous Enquiries are stored in the report for a duration of 2 years from the inquiry date.
- Information concerning the timeliness of monthly repayments for existing accounts is presented on a rolling 12-month basis.
- Closed credit accounts depict the payment status history for the last 12 months as of the closure date, and this information is preserved for a period of 3 years.
- Default records uploaded by Members with the status of Negotiated Settlement or Full Settlement remain on record for 3 years from the settlement date.
- Default records with the status of Outstanding and Partial Payment, however, are retained indefinitely on your credit file.
- If applicable, bankruptcy data is visible for 5 years from the date of discharge.
Conclusion
Understanding your credit score and how it impacts your financial life is crucial in Singapore's lending landscape. By monitoring your credit score, adhering to responsible financial practices, and managing your existing credit wisely, you can enhance your creditworthiness and secure more favorable loan terms. Always remember to assess your lender's loan offerings to ensure you are getting the best possible deal. At Lendingpot, we strive to provide competitive loan packages that align with our customers' needs.