

Did they promise to call?
A modern horror story.
“Oh, yes! We will certainly try our best to grant you the loan. Just submit the documents and we’ll let you know within 48 hours if you qualify!” says a chirpy voice.
Painstakingly, the business owner gathered all required documents from varied sources and submitted them after 2 weeks.
Another week goes by, going back and forth over e-mail about missing or erroneous documents.
She promises to call back after receiving all the documents but actually, she has already shredded your documents.
That, unfortunately, will be the last time you hear from anybody from the bank.
This is the “Slow No”. The silent business loan rejection.
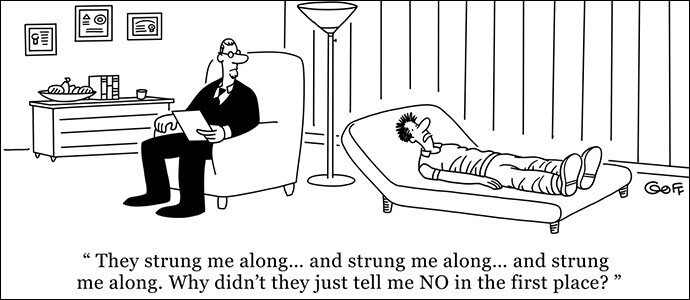
Cartoon from US business loan info website
The reasons are simple
Dealing with a bank is often a confusing love-hate relationship. You need them, businesses can’t function without them. But at the same time, you don’t feel that they are helping you when you need them.
The “Slow No” often happens when the effort-versus-reward scale is not balanced; where there are minimal rewards for serving a client who doesn’t qualify for the loan.
Moreover, when you apply online directly, your request is handled by a digital administrator who processes these leads before passing it to a relationship manager.
Without an existing connection, it is easy for the relationship manager to ignore the applications from companies that are not eligible for a business loan.
(Many banks use strict criteria to govern business loan eligibility - e.g. not profitable in the last financial year, no unsecured loans. Thus, it is easy to determine eligibility in a non-ambiguous manner.)
Stop waiting for the business loan decision. Here are 3 things you can do to get the answers you need.
1. Call your relationship manager
Do so if you have his or her contact details, but please be nice. Relationship managers are almost always overworked with a portfolio of clients to handle. But more importantly, remember that he or she is your advocate in the bank, so being nice is never a bad idea.
2. Don’t wait for your preferred bank, apply to multiple banks, financial institutions or fintech companies
Like job applications, the more you send out the better your situation will be. If you don’t get a response from the local incumbents (who are often pickier), there are still smaller and hungrier institutions who might reply.
3. Hire a business loan broker
This is a good option if you can afford it. Brokers usually charge around 2-5% of the approved loan amount, but collect only if they manage to get the loan for you. Contracts will be signed to prevent disputes.
Photo credit: pexel
4 More Ways To Improve Your Chances Of Getting A Business Loan in Singapore
5 Reasons Why You Can’t Get That Business Loan in Singapore
How Can You Make Factoring Work For Your Company? (Branded Content)
Request for a Business Loan Now!
Lendingpot.sg operates a Business Loan Marketplace that allows an SME to connect to multiple lenders with just one application, allowing the SME to know who its prospective lenders are and the rates that they offer, in a very short time.