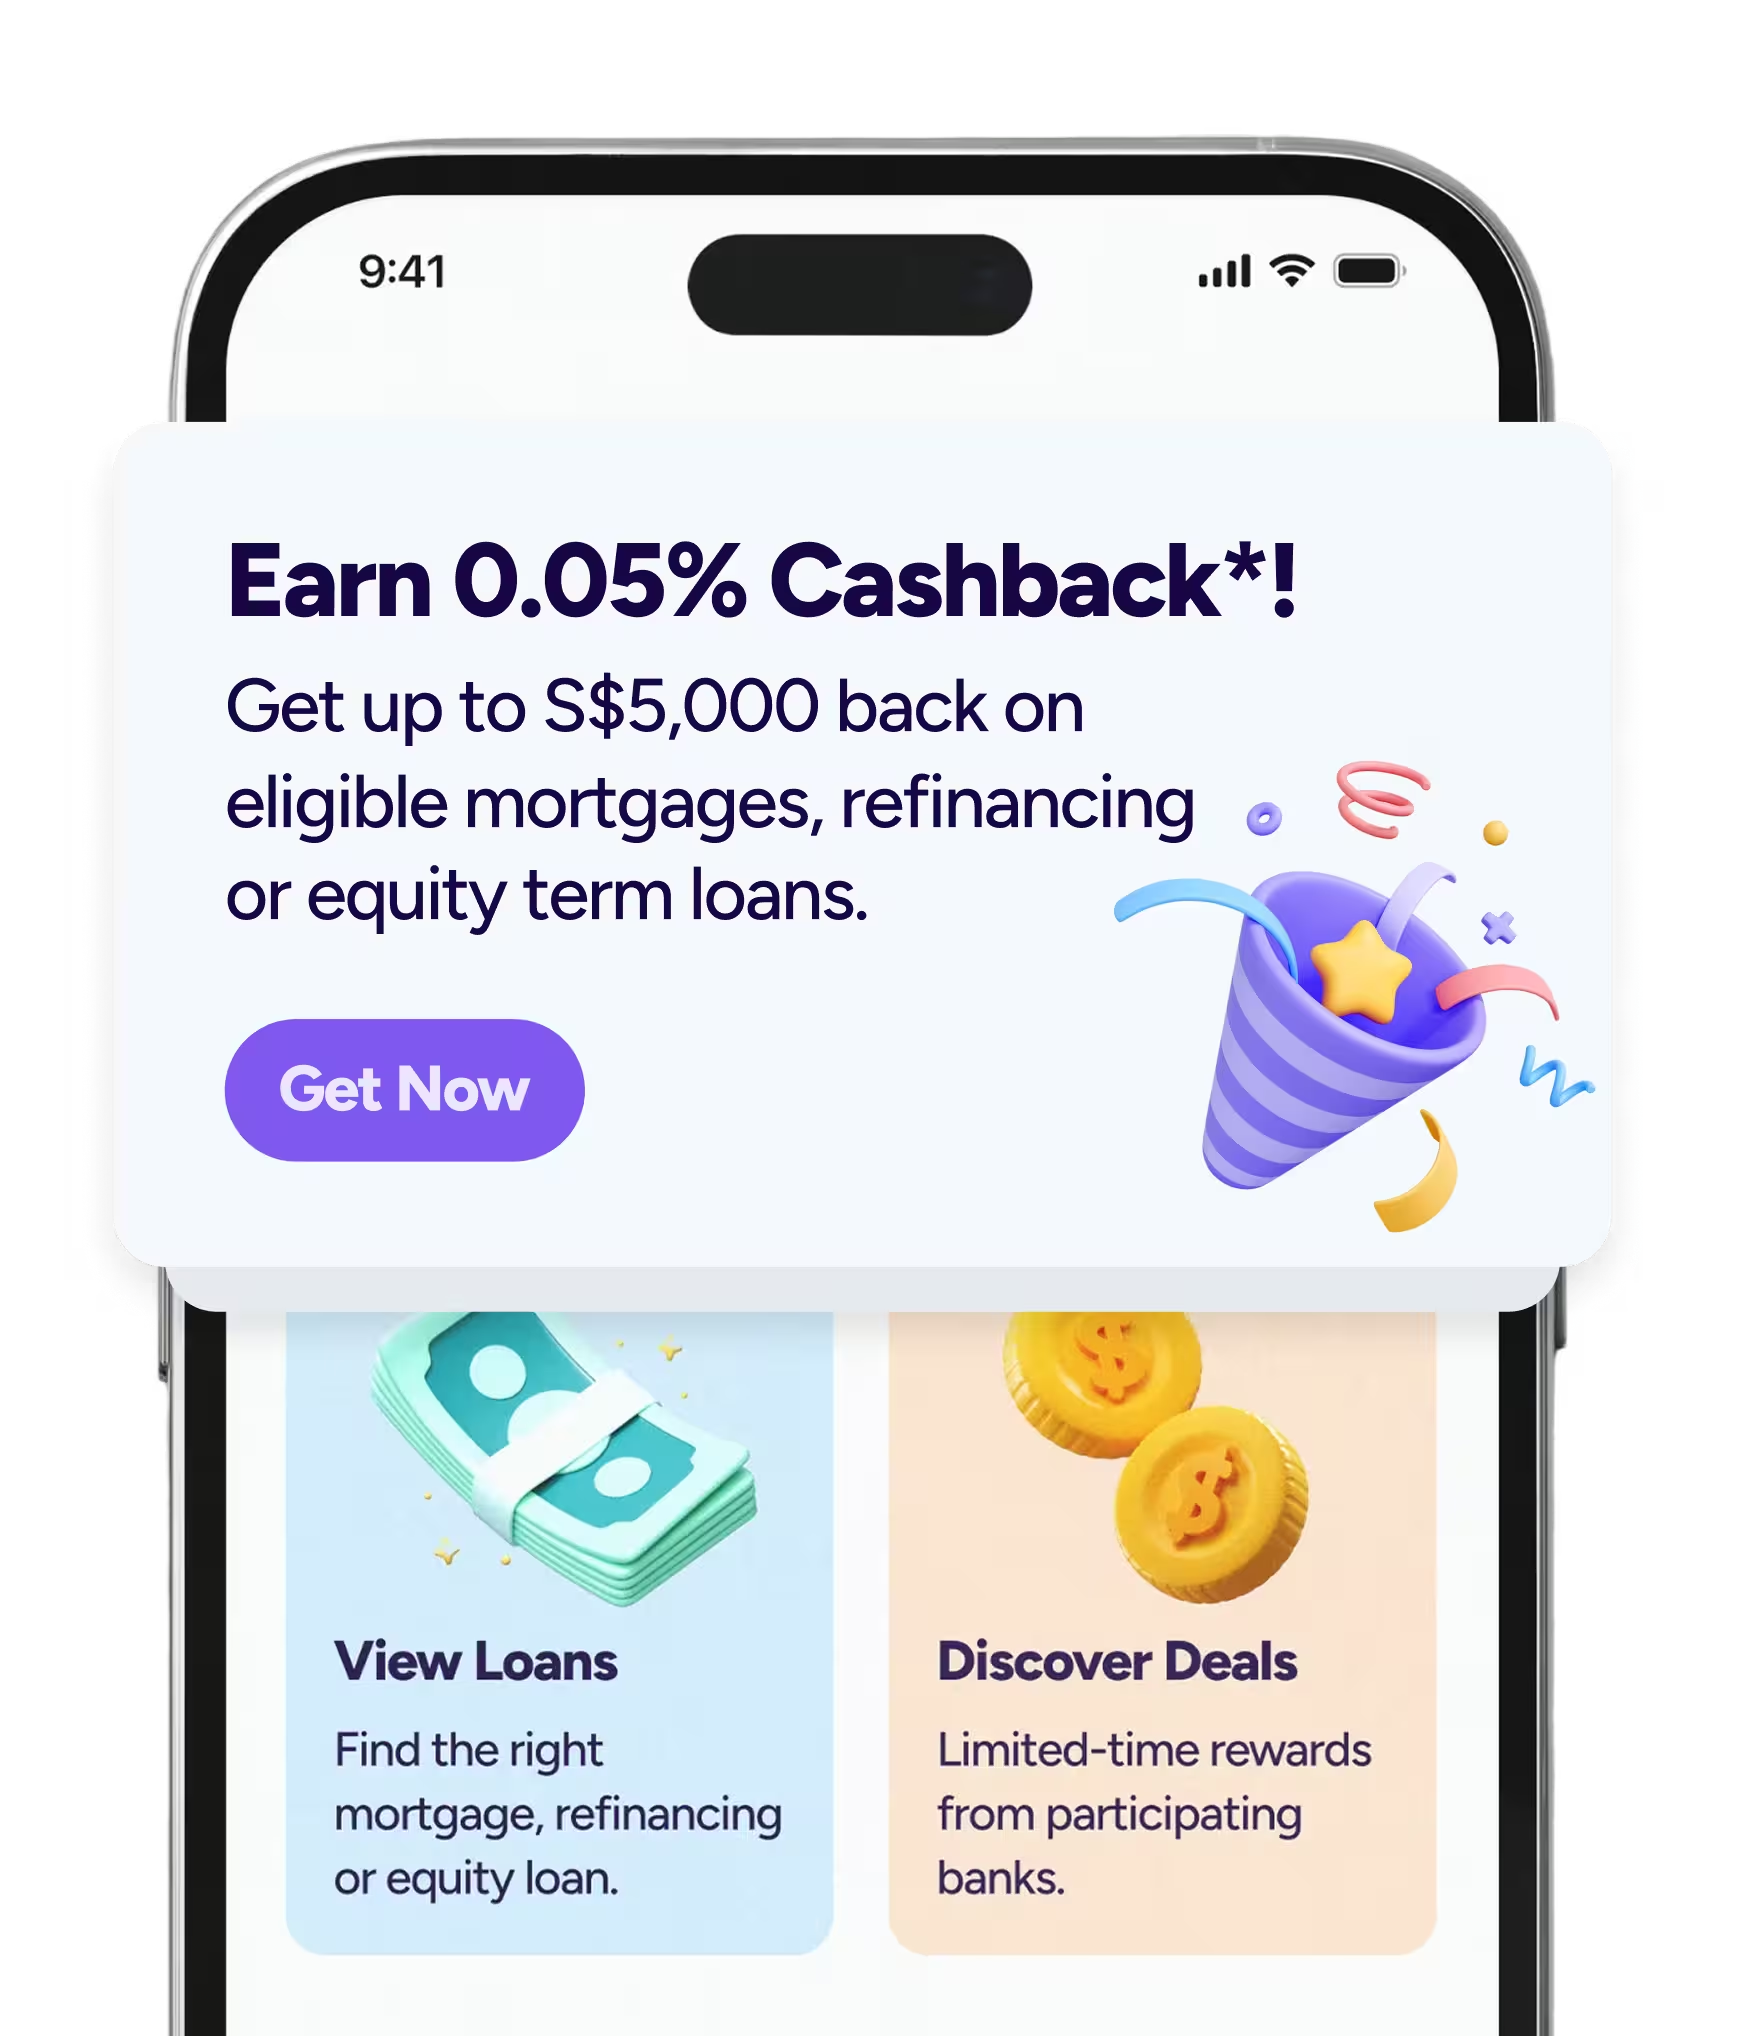
*Eligible home loans above S$500,000 only. Cashback capped at S$5,000. Terms apply.
Why Use Lendingpot For Your Mortgage Refinancing
Banks Compete For You
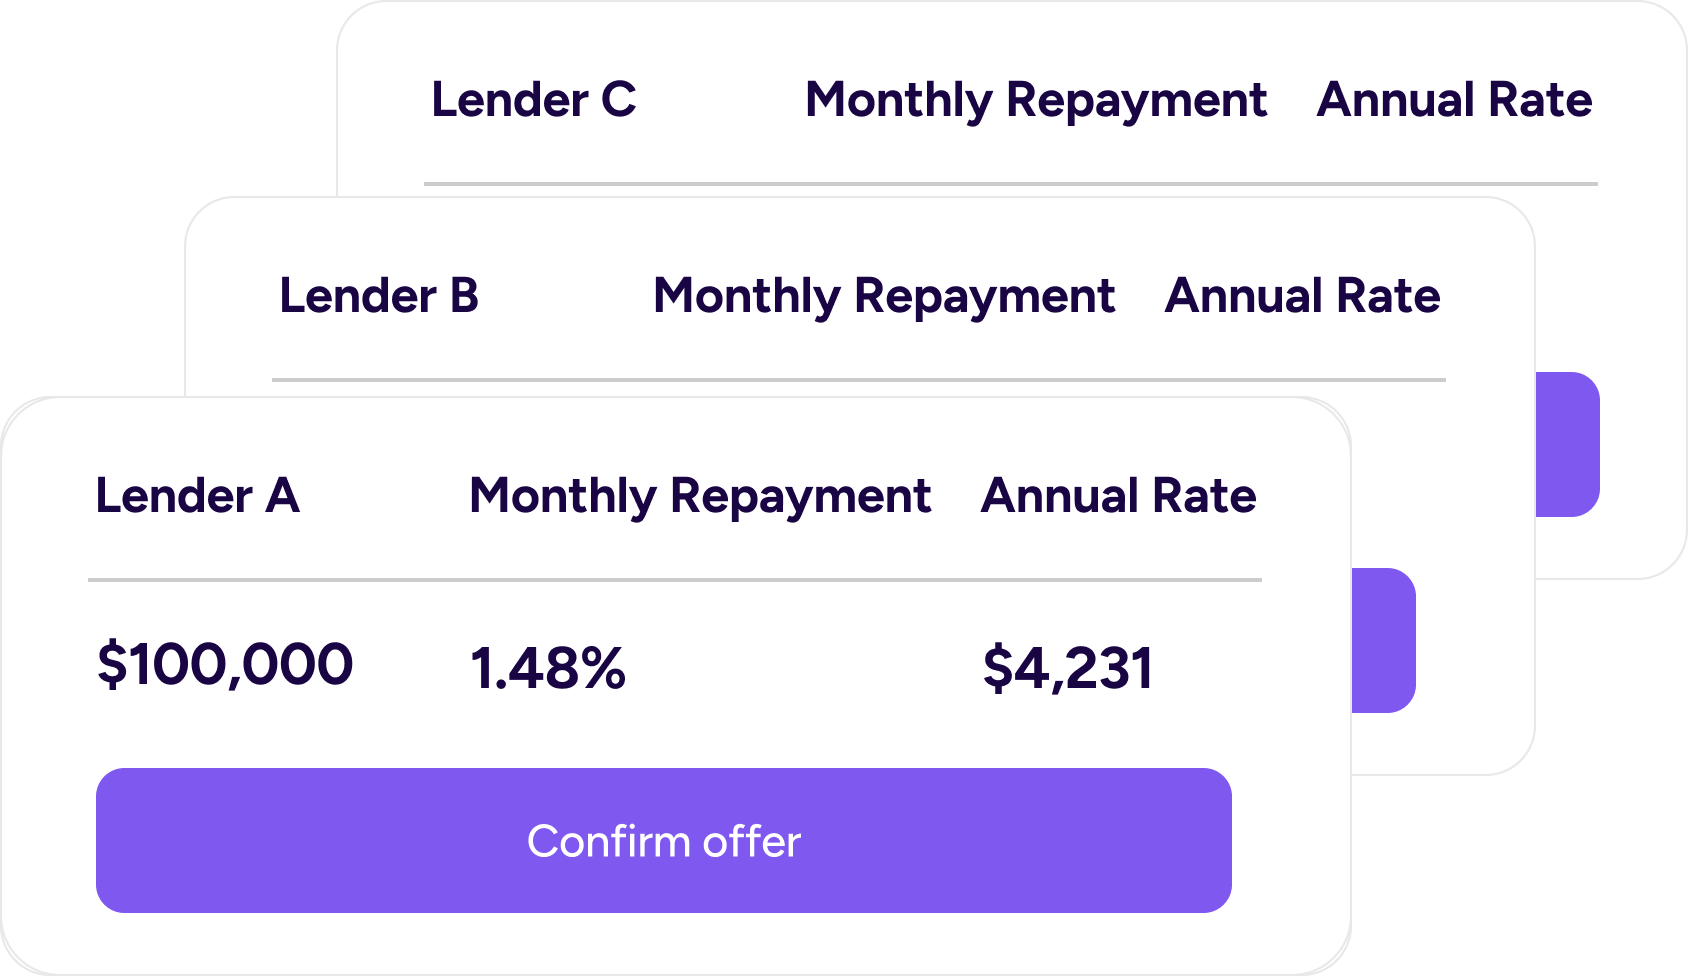
We broadcast your request to our entire network. Lenders know you are comparing, so they offer their best "new customer" rates to win your business.
No Hidden Costs
We look for packages that include legal and valuation subsidies. These can cover your switching costs almost entirely, so you don't have to pay out of your own pocket.
Expert Rate Strategy
We help you navigate the 2026 SORA benchmarks so you can lock in a better rate when the market dips.
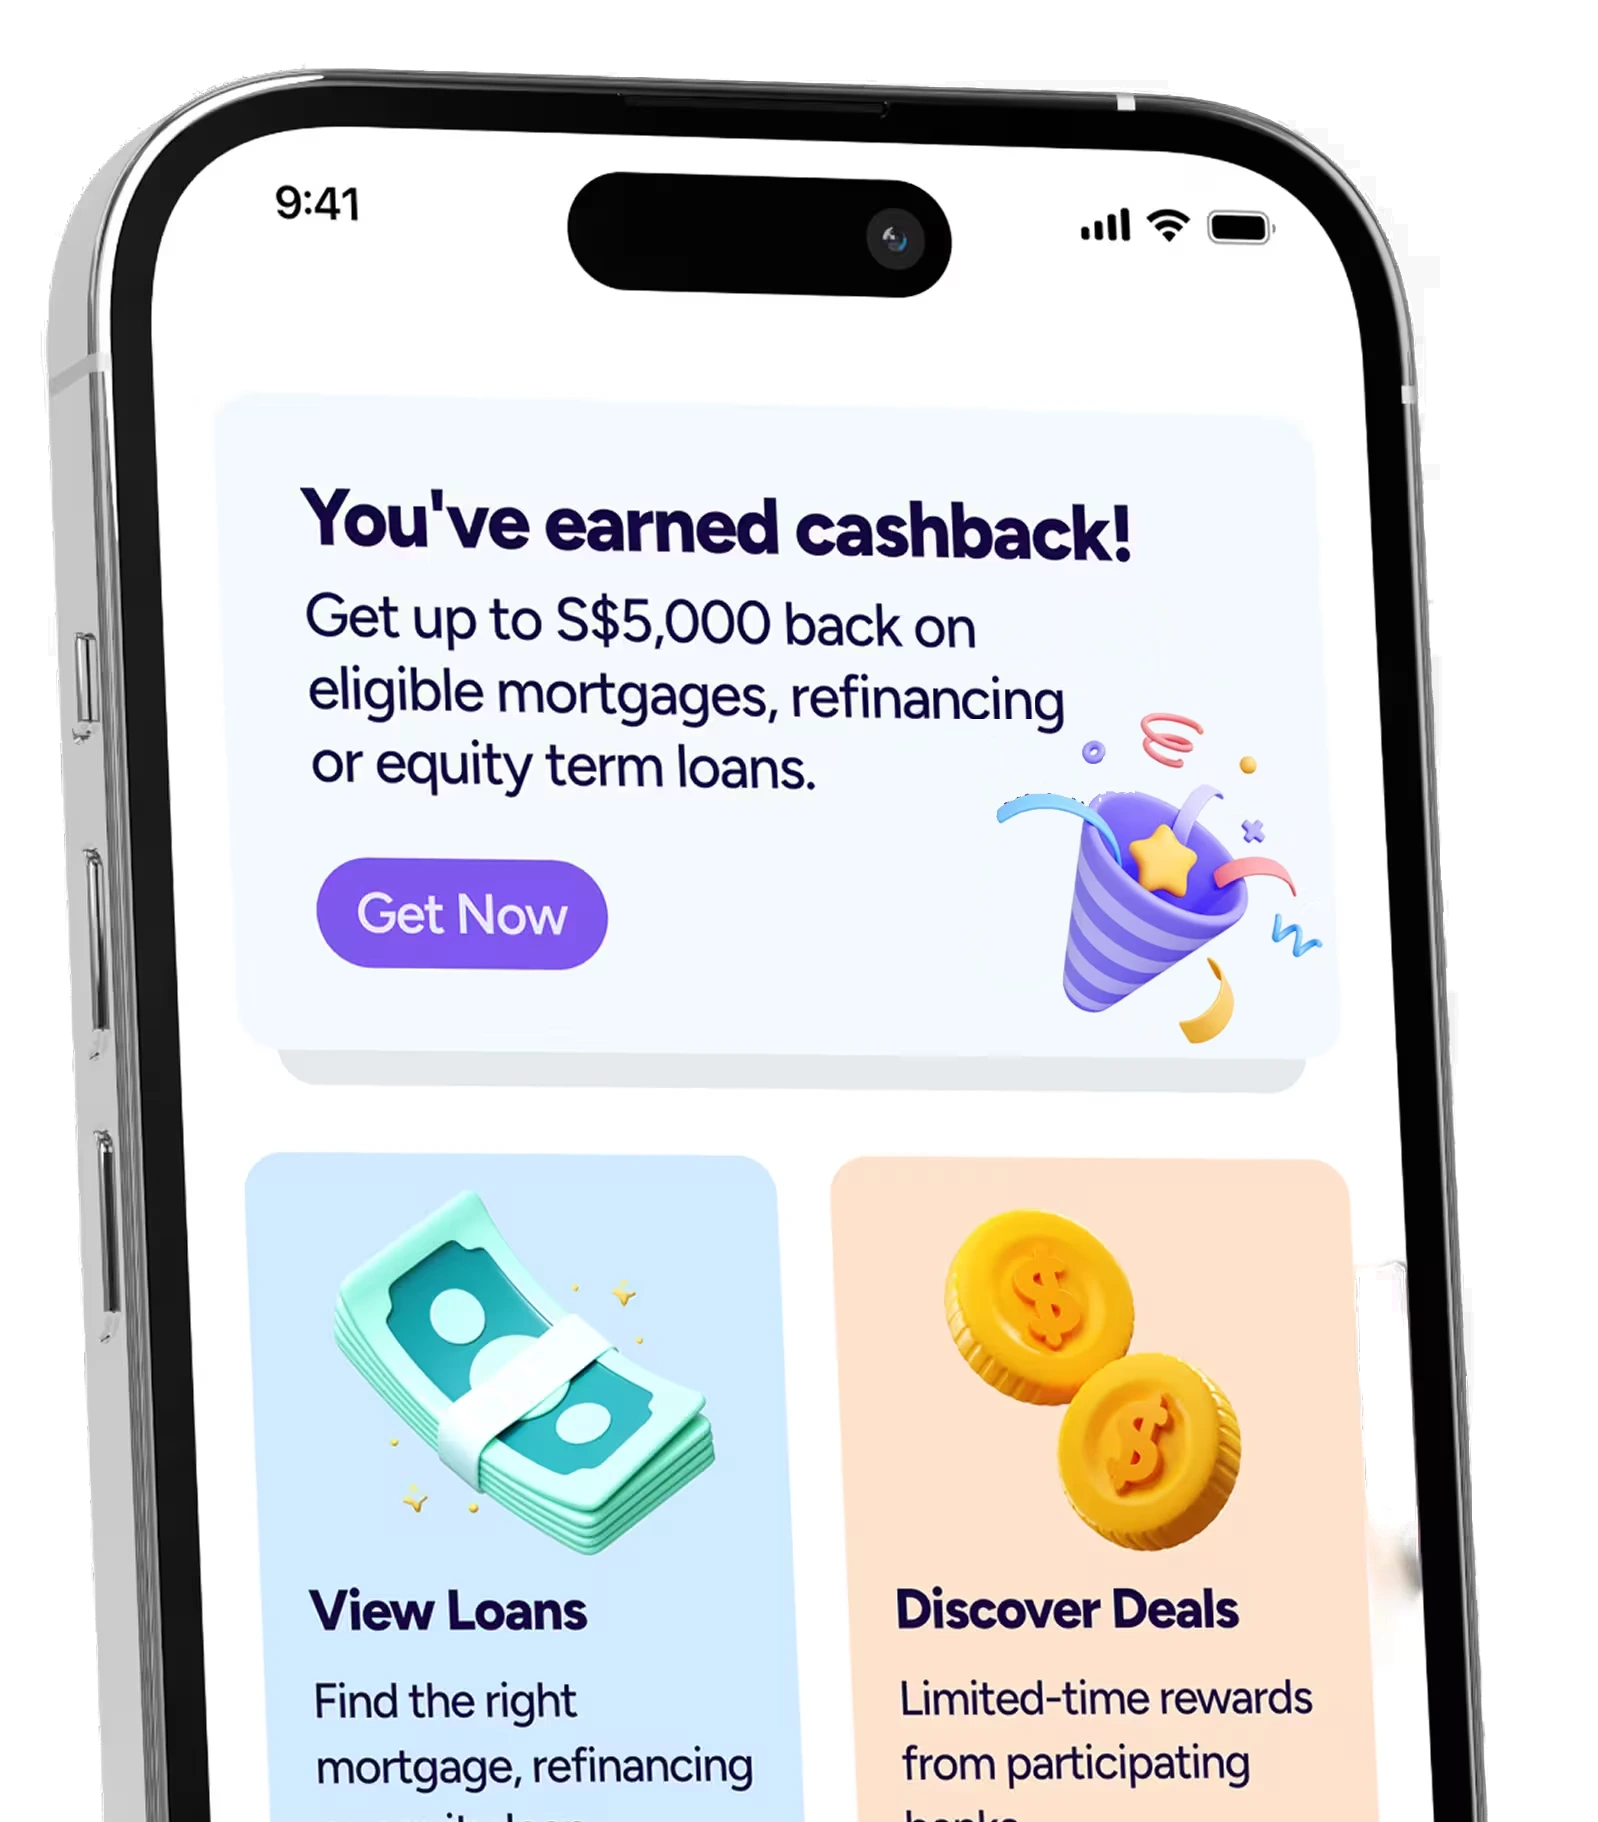
Receive 0.05% Cashback*
Successfully secure your home loan through Lendingpot and enjoy 0.05% cashback on your approved loan amount.*
Rates shown above are Effective Interest Rates (EIR).
Actual rates and repayments may vary. Subject to the
lender's final assessment.
Calculate Your Monthly Loan Repayments
Use our calculator to get a clear view of your potential repayment schedule for a loan in Singapore.
Difference Between Refinancing for Private Property and HDB
Private Property
HDBs
Eligible as private properties can only be financed by banks
You can refinance from a HDB concessionary loan to a bank loan. However, you cannot refinance a bank loan to a HDB concessionary loan. Bank to bank refinancing is eligible.
When Should You Start Looking to Refinance?
Ideally, you should start comparing refinancing rates 4 to 6 months before your lock-in period expires. This timeline gives you ample buffer to complete the necessary paperwork and serve your current bank their required 3-month redemption notice period. Starting early ensures you transition seamlessly the day your lock-in ends, allowing you to avoid hefty prepayment penalties or being automatically rolled over into significantly higher, volatile floating rates.
NRIC for Singaporeans/PRs or Passport and Employment Pass for Foreigners
Income Proof (Self-Employed)
Latest 2 years of Notice of Assessment (NOA) from IRAS.
Income Proof (Salaried)
Latest 3 to 6 months of computerised payslips and your most recent CPF Contribution History Statement.
Current Home Loan Details
Your most recent loan statements showing your outstanding balance and remaining tenure.
Proof of Ownership of Property
A copy of your property title deed or HDB ownership documents
How Our Mortgage Refinancing In Singapore Works
Message Us On WhatsApp
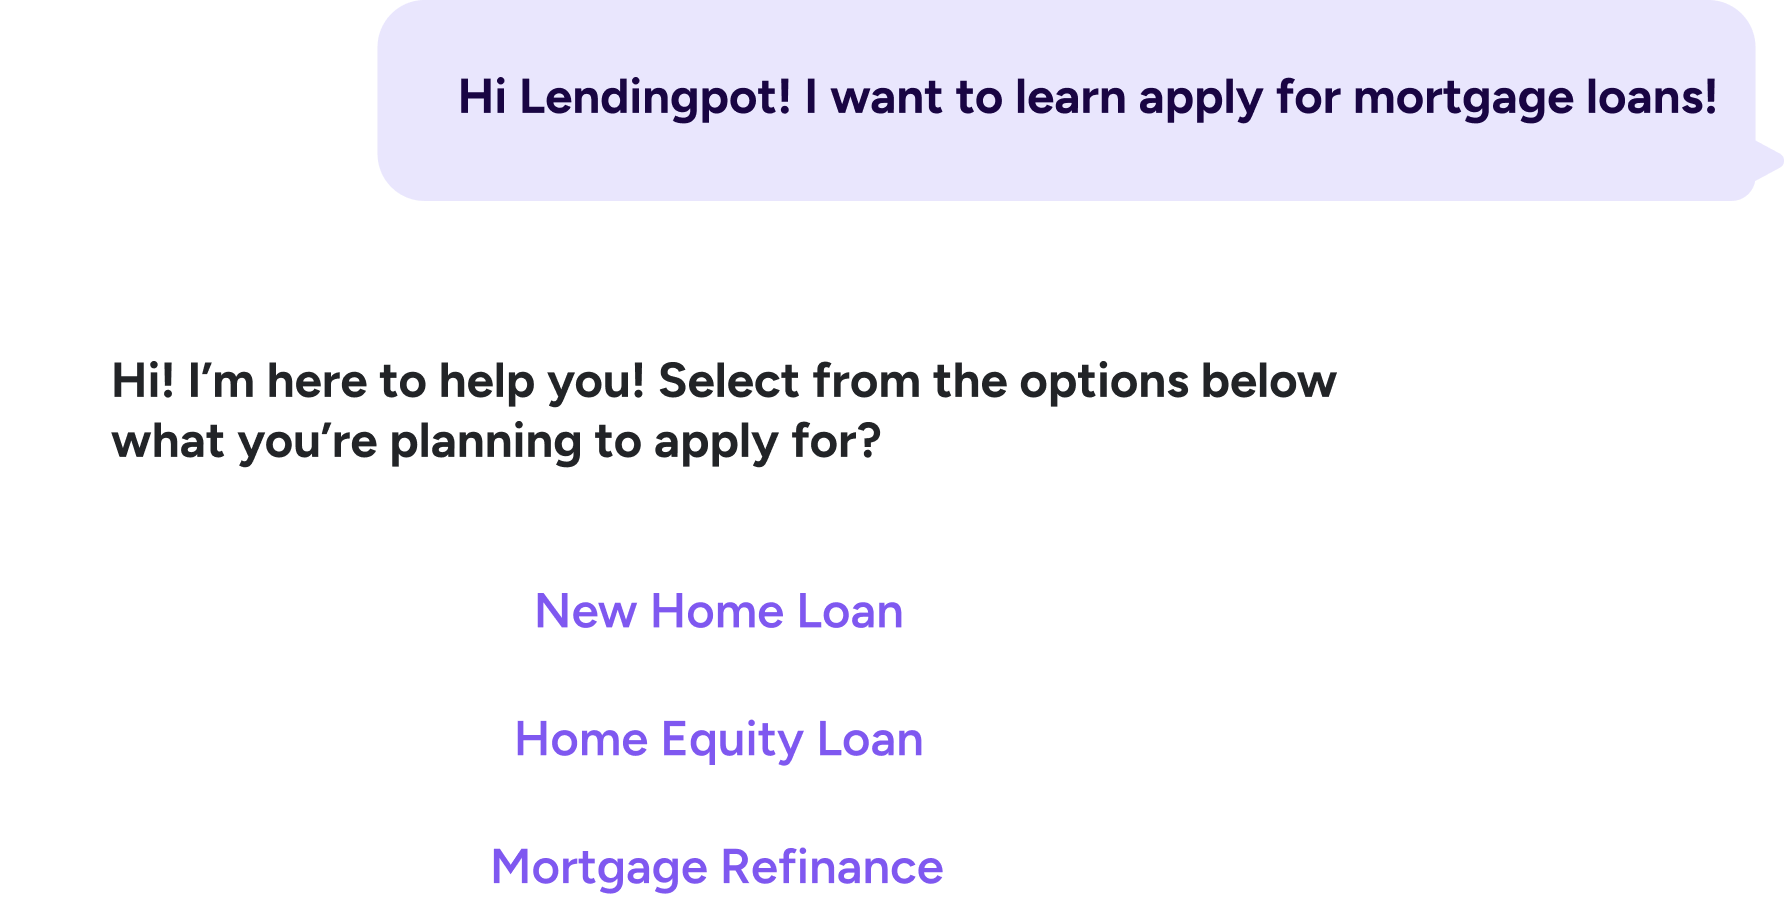
First, start by indicating your home loan needs, whether it's a new purchase or a refinance.
Get Personalised Rates
Our friendly agent will connect with you to understand your needs and share home loan options and rates, especially for you!
Choose Your Best Option
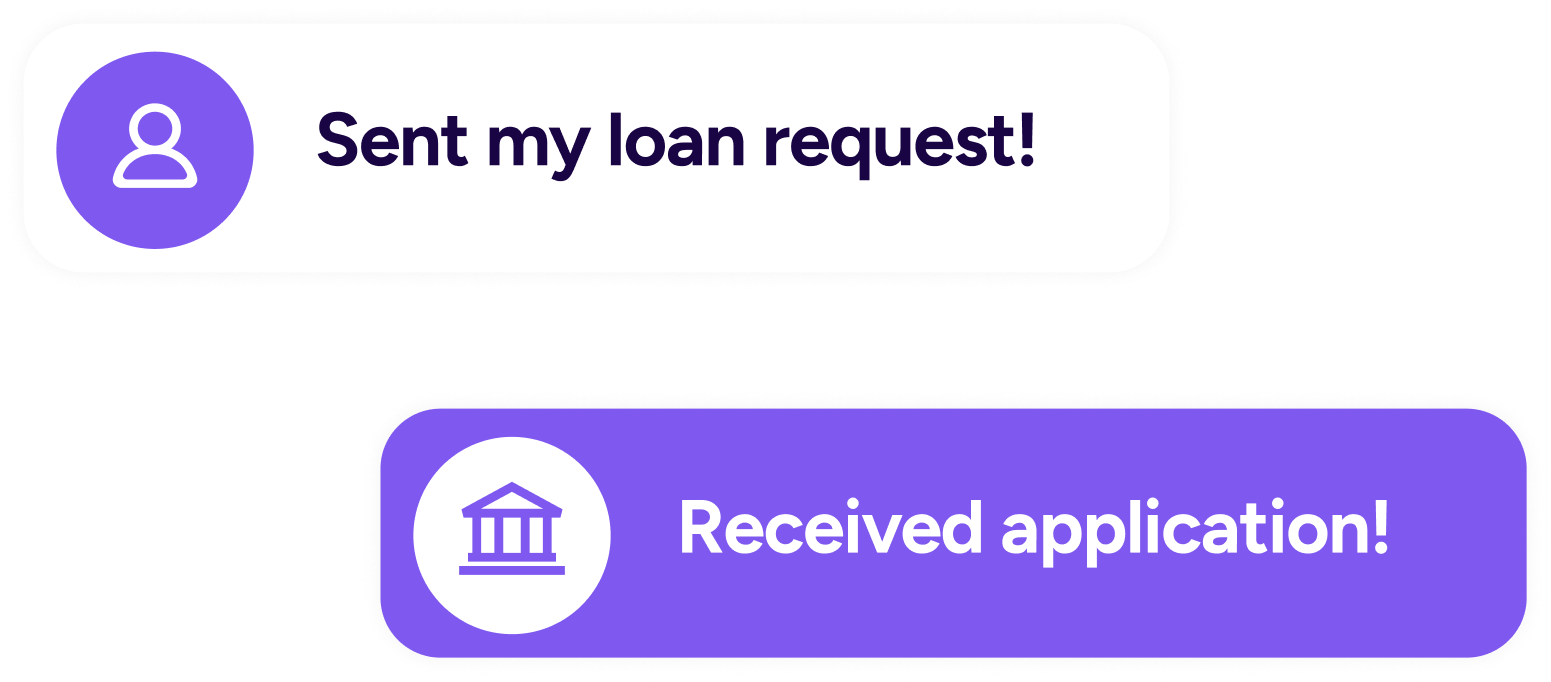
When you're ready to proceed, your contact details will be securely sent to the chosen bank, ensuring a seamless transition from inquiry to application.
Secure Your Mortgage
After accepting your preferred offer, our mortgage specialist will guide you through the application, documentation, and completion process until your loan is successfully disbursed.
Receive Your Cashback
Once your eligibility has been verified, the 0.05% cashback* will be credited according to the promotion fulfilment timeline.
Receive 0.05% cashback on eligible mortgage loans, mortgage refinancing or equity term loans arranged through Lendingpot with participating banks. The loan amount must exceed S$500,000, and cashback is capped at S$5,000.
The promotion is available to Singapore residents who submit their enquiry through Lendingpot, successfully obtain final and unconditional approval, complete the loan through an eligible partner bank and submit a Google Review of their experience.
Cashback will be credited to the eligible customer’s bank account within 90 days after the campaign ends, subject to verification and submission of the required loan and bank account details.
Participating banks include DBS, Standard Chartered, UOB, OCBC, CIMB, RHB, Maybank and HSBC.
The promotion cannot be combined with other offers. Credit criteria, fees, charges, eligibility requirements and exclusions apply.
Loans arranged outside Lendingpot are not eligible, and Lendingpot reserves the right to amend or withdraw the promotion.
Who Can Apply for Mortgage Refinancing
Homeowners Out of Their "Lock-in" Period
If your current home loan is more than 2 or 3 years old, you are likely out of your lock-in period. This is the "sweet spot" for applying for mortgage refinancing in Singapore, as you can switch banks without paying a penalty.
Owners of HDB Flats or Private Property
Whether you live in a 4-room HDB or a luxury condo, you are eligible. However, if you are currently on an HDB HSR loan, you can only switch to a bank; you cannot switch from a bank loan back to an HDB loan.
Those With A Loan Balance of At Least $200,000
Most banks in Singapore look for a remaining loan of at least $200,000. This ensures the interest savings are large enough to make the switch worth the paperwork.
Employed Individuals With Stable Income
Banks want to see that you can still afford your payments. As long as your total monthly debts (including the new mortgage) stay under 55% of your monthly income, you are generally eligible to apply.
Singapore Citizens and Permanent Residents (PR)
Most mortgage refinancing packages are available to Singapore Citizens and Permanent Residents.
Age Range
Applicants must generally be between 21 and 65 years old at the time of application or loan maturity.
Refinance Your Mortgage In Singapore With Zero Fees
We have created a simple and risk-free way for you to lower your monthly home loan payments without the usual bank headaches or confusing jargon.
Check Multiple Banks at Once
We send your request to our entire network of major banks in Singapore. This makes them compete to offer you the lowest possible interest rates for mortgage refinancing in Singapore, ensuring you get the best deal available.
Banks often use complicated math to hide the true cost of a loan. We break everything down into clear numbers so you can easily see which offer saves you the most money over time and never overpay.
Whether you want to shorten your loan tenure, lower your monthly bills, or switch from a floating rate to a fixed one, we find the right mortgage refinancing in Singapore that fits your needs.
Your mortgage is likely your highest monthly cost. Secure your future by locking in a better mortgage refinancing rate in Singapore today. Get the lowest rates and protect your lifestyle.
Usually, one must pay for valuation and legal expenses. Some banks may additionally levy a one-time processing fee for commercial properties. There may be additional costs in unique situations. However, the subsidies provided by the new bank can typically cover the cost, in whole or in part. To prevent you from paying extra or hidden fees now or in the future, we make sure you understand all charges and translate any technical terms.
When should I refinance my mortgage?
Generally speaking, if your lock-in and claw-back periods on your mortgage loan are about to end, or if there is a significant disparity between your loan interest rate and current market rates, it is a good time to refinance. If unsure, don't hesitate to get in touch with us for a free consultation.
How much does it cost to refinance a mortgage?
For private properties, legal and valuation fees typically range between $2,500 and $3,000. For HDB, it’s about $1,500 to $1,800. However, many banks offer cash rebates or subsidies to cover these costs if your loan amount is high enough.
How soon can I refinance in Singapore?
Most banks require a 3-month notice period before you switch. It is best to start comparing rates about 4 to 6 months before your "lock-in" period ends so you can time the move perfectly and avoid penalties.
What are the requirements for a mortgage refinance?
You generally need a minimum loan amount of $200,000 for HDB or $300,000 for private property. You must also pass the Total Debt Servicing Ratio (TDSR) check, which ensures your total monthly debt payments don't exceed 55% of your gross income.
How does refinancing work in Singapore?
Refinancing a mortgage involves moving your existing home loan to a new bank to enjoy a lower interest rate or better terms. This new bank pays off your old loan, and you start making lower monthly payments to the new lender.
Best Mortgage Loan Articles
Mortgage Loans
How Singapore’s Licensed Moneylenders Serve the Underserved
Michelle Zhu
March 3, 2026
Mortgage Loans
When Should You Refinance to Get the Best Mortgage Rates?
Lina Tay
June 3, 2025
Mortgage Loans
Types of Bank Interest Rates for Mortgage Loans in Singapore